Buying a home is one of the biggest financial decisions most people make. For many buyers, a home loan is an important part of making that purchase possible.
During the home-buying process, you may come across terms such as home loan pre-approval, loan sanction, disbursement and property verification. These terms can sound similar, but they refer to different stages of the financing process.
Understanding the difference between home loan pre-approval and final sanction can help you plan your property purchase more confidently.
What Is Home Loan Pre-Approval?
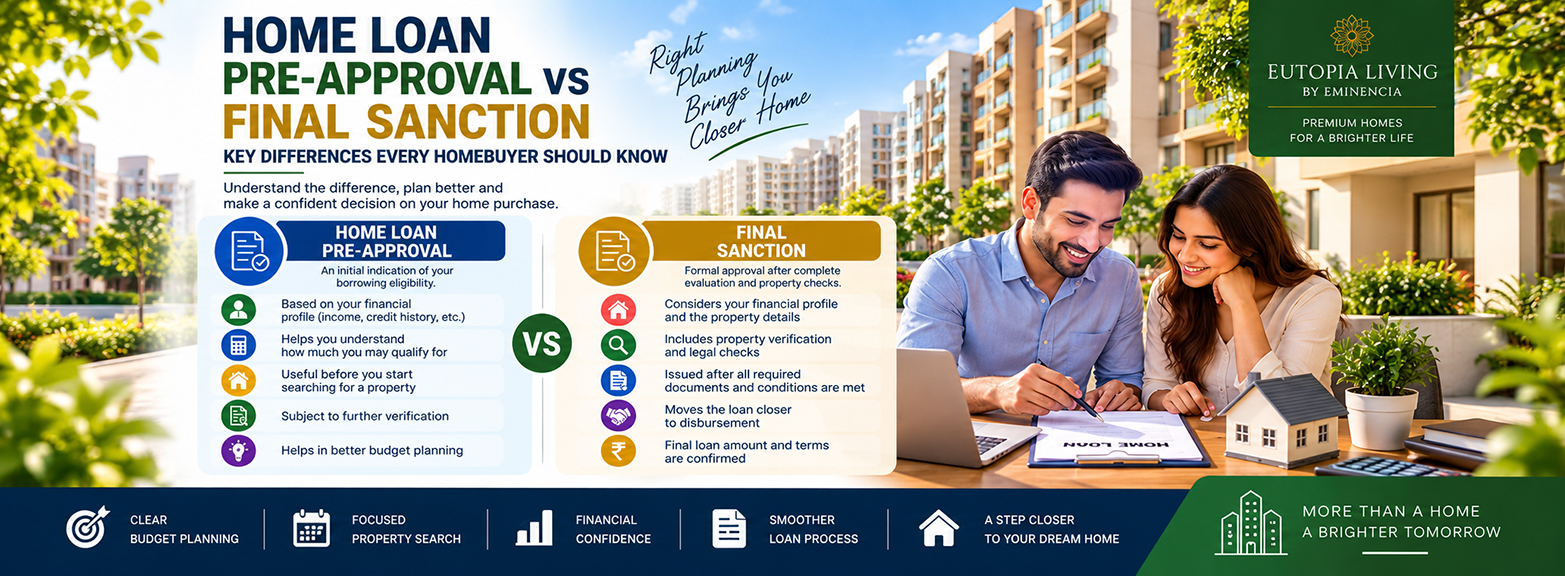
A home loan pre-approval is an initial indication from a lender that you may be eligible for a particular loan amount based on the financial information you provide.
The lender may consider factors such as:
- Income
- Employment or business profile
- Existing loans
- Credit history
- Age
- Repayment capacity
- Financial documents
A pre-approval can give a buyer an idea of how much financing they may potentially qualify for.
However, pre-approval should not automatically be treated as final loan approval.
Why Is Pre-Approval Useful?
Getting an indication of your potential borrowing capacity before selecting a property can make your home search more focused.
For example, if you know the approximate loan amount you may qualify for, you can better estimate:
- Your property budget
- Your expected down payment
- Possible monthly repayment
- Additional purchase expenses
- How much savings you should keep available
This can help prevent buyers from selecting a property that is beyond their practical financial capacity.
What Is Final Home Loan Sanction?
Final loan sanction generally comes after the lender has completed its required assessment of the borrower and the property.
The lender may review both:
The borrower and The property
This distinction is important because being financially eligible does not necessarily mean every property will receive financing under the same terms.
The lender may require property-related documents and conduct its own verification before proceeding.
Pre-Approval vs Final Sanction
Here is a simple way to understand the difference:
The exact process can vary between lenders, so buyers should always confirm the applicable requirements directly with their financial institution.
What Does the Bank Check?
When processing a home loan, lenders generally evaluate the applicant’s financial profile.
Depending on the lender and application, this may include:
Income
Your income helps the lender assess your repayment capacity.
Salaried applicants may be asked for salary-related documents, while self-employed applicants may need to provide business and income records.
Credit History
Your credit history can be an important part of the lender’s assessment.
A strong repayment history may support your application, while outstanding or delayed payments can affect the lender’s decision.
Existing Financial Commitments
If you already have loans or other significant financial obligations, the lender may consider these when evaluating your repayment capacity.
Employment or Business Stability
Lenders may also review employment or business-related information as part of their assessment.
Why Property Verification Matters
One of the biggest differences between an initial financial assessment and final loan processing is the property itself.
After selecting a flat, the lender may need to review relevant property documents and other information.
Depending on the project and lender, this could involve checking matters related to:
- Property ownership
- Project documentation
- Approved plans
- Sale or purchase documents
- Property valuation
- Legal documentation
- Builder or developer information
The exact requirements depend on the lender, property and transaction.
Don’t Confuse Loan Amount With Property Budget
Suppose a lender indicates that you may qualify for a particular loan amount.
That does not necessarily mean you should purchase a property at the maximum possible price.
You should also consider:
- Your available savings
- Down payment
- Registration-related expenses
- Interior costs
- Moving expenses
- Maintenance
- Emergency savings
- Existing financial commitments
A comfortable home budget should take your overall financial situation into account rather than relying only on the maximum loan amount.
What Happens After Loan Sanction?
Once the loan is sanctioned and the required conditions are completed, the process can move toward documentation and disbursement.
Depending on the property and transaction, the lender may require additional documents before releasing funds.
For an under-construction property, the disbursement process may also be linked to the applicable construction or payment schedule.
Buyers should understand the lender’s terms before signing financial commitments.
Questions to Ask Your Lender
Before proceeding with a home loan, consider asking:
- What loan amount am I eligible for?
- Is this an initial pre-approval or final sanction?
- What documents are required?
- What property documents will be checked?
- What conditions must be completed before disbursement?
- What additional charges apply?
- What happens if the property valuation differs from expectations?
- What is the expected processing timeline?
- Can the sanctioned amount change before disbursement?
- What happens if the property purchase is delayed?
Getting clear answers can help you avoid surprises later.
Home Loan Planning for Flat Buyers in Patiala
If you are planning to buy a flat in Patiala, financing should be considered alongside location, apartment size, amenities and overall property cost.
Instead of waiting until you have finalized every detail, understanding your potential borrowing capacity early can help you shortlist properties more realistically.
However, buyers should always verify the latest loan terms, eligibility criteria, interest rates and documentation requirements directly with their chosen lender.
A Simple Home Loan Checklist
Before moving ahead with your apartment purchase, keep these points in mind:
- Check your overall budget.
- Understand your potential loan eligibility.
- Keep funds ready for the down payment.
- Maintain an emergency reserve.
- Compare suitable lenders.
- Understand processing and other applicable charges.
- Check property documentation.
- Read the sanction terms carefully.
- Understand the disbursement process.
- Keep copies of all important documents.
Final Thoughts
A home loan pre-approval and a final loan sanction are not necessarily the same thing.
Pre-approval can help you understand your potential purchasing capacity, while final sanction generally involves a more detailed assessment of the borrower and the selected property.
For prospective homebuyers, understanding this distinction can make the property-buying process more organized and financially informed.
Whether you are looking for a new flat in Patiala or considering a residential project elsewhere, take time to understand your financing position before making a major property commitment.
Frequently Asked Questions
Is pre-approval the same as final home loan approval?
No. Pre-approval is generally an initial indication based on available financial information, while final sanction can involve additional borrower and property verification.
Can a pre-approved home loan be rejected later?
Yes. Further assessment, documentation, property verification or changes in the applicant’s circumstances can affect the final decision.
Should I get pre-approved before looking for a flat?
It can be useful because it gives you a better understanding of your potential borrowing capacity and helps you plan your property budget.
Does the bank check the property before final sanction?
Property-related verification may be part of the lender’s process. Requirements vary depending on the lender and property.
Should I borrow the maximum amount I am eligible for?
Not necessarily. Your comfortable budget should also consider your savings, down payment, other expenses and existing financial commitments.